How funding rate arbitrage works
Perpetual futures pay funding between longs and shorts every 1, 4 or 8 hours. When the rate is positive, longs pay shorts. Different exchanges often charge different rates for the same coin. If you short where funding is high and go long the same amount where it is low, price moves cancel out and you collect the difference.
Daily income = position × (short-leg rate × 24 / interval − long-leg rate × 24 / interval). Fees = 4 × position × taker fee. The calculator normalises 1h, 4h and 8h intervals to 24 hours so they can be compared.
Example: $10,000 per leg, short at +0.03% per 8h, long at +0.005% per 8h. The gap is 0.025% per 8h, or 0.075% a day: $7.50 per day. Four taker orders at 0.05% cost $20, so it takes under three days to break even.
Risks the calculator doesn't show
- Rates change every interval and can flip sign. The live funding scanner shows where they are now.
- Price gap between the two contracts when you open and close. Check the arbitrage scanner.
- Liquidation: each leg is margined separately, so a sharp move can liquidate one leg. Use low leverage; see the liquidation calculator.
Full walkthrough: Funding rate arbitrage: a step-by-step guide.
Questions
Is funding rate arbitrage risk-free?
No. It removes most price risk, but rates change every interval, the two contracts can drift apart, fees add up, and either leg can be liquidated if leverage is too high.
How is APR calculated here?
Net profit for the period divided by the margin used on both legs (position ÷ leverage × 2), scaled to a year.
Where can I see live funding rates?
On ArbiLayer's funding page, which compares perpetual funding on 20+ exchanges normalised to 24 hours and APR.
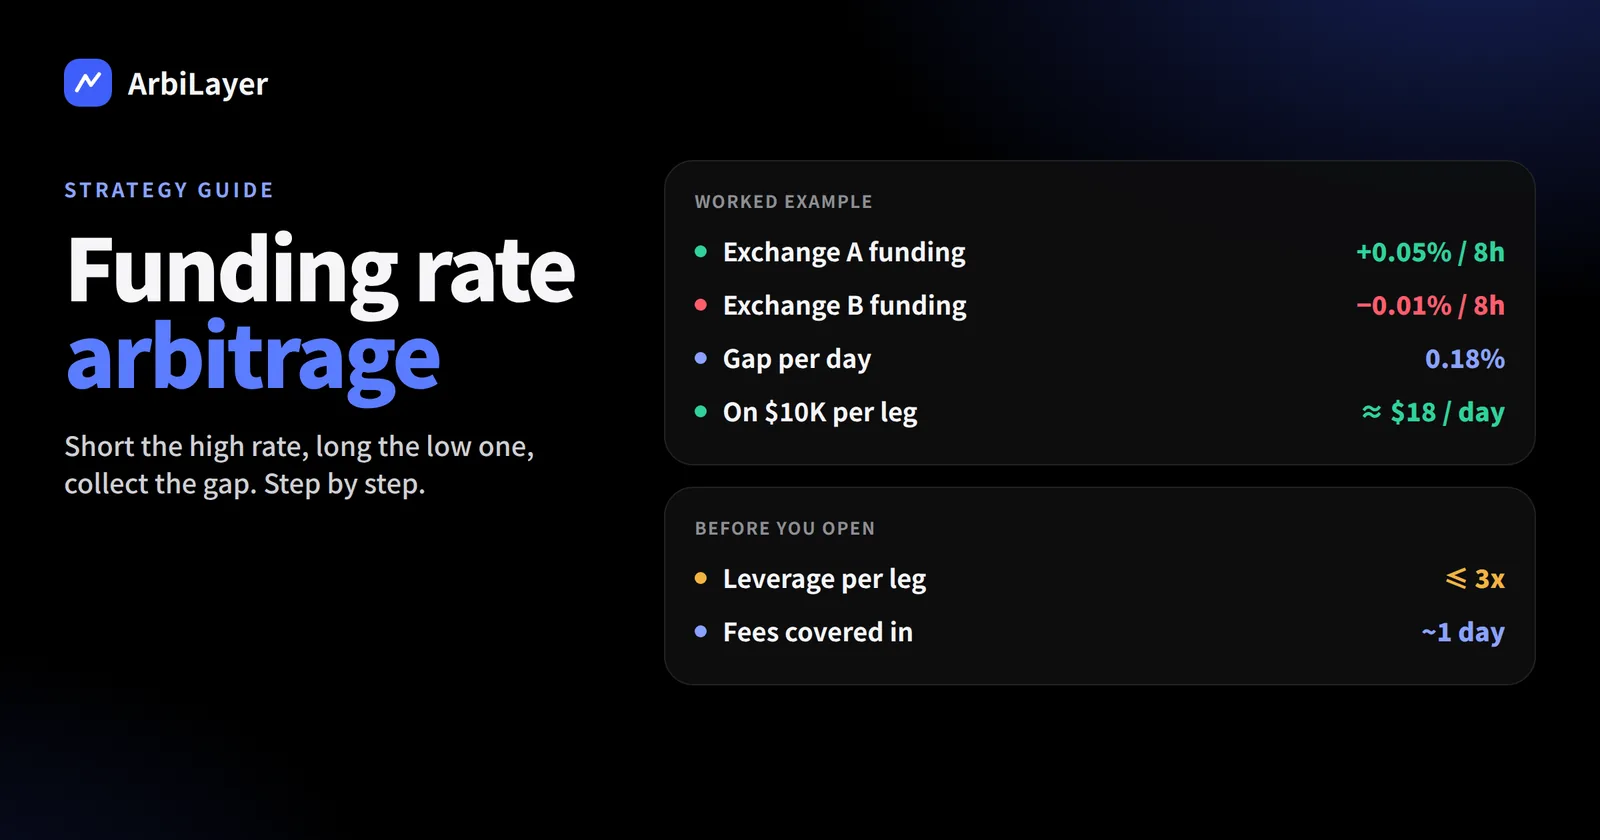 Funding Rate Arbitrage: A Step-by-Step GuideHow funding rate arbitrage works: short where funding is high, long where it is low, collect the gap. The maths, a worked example, how to fi…
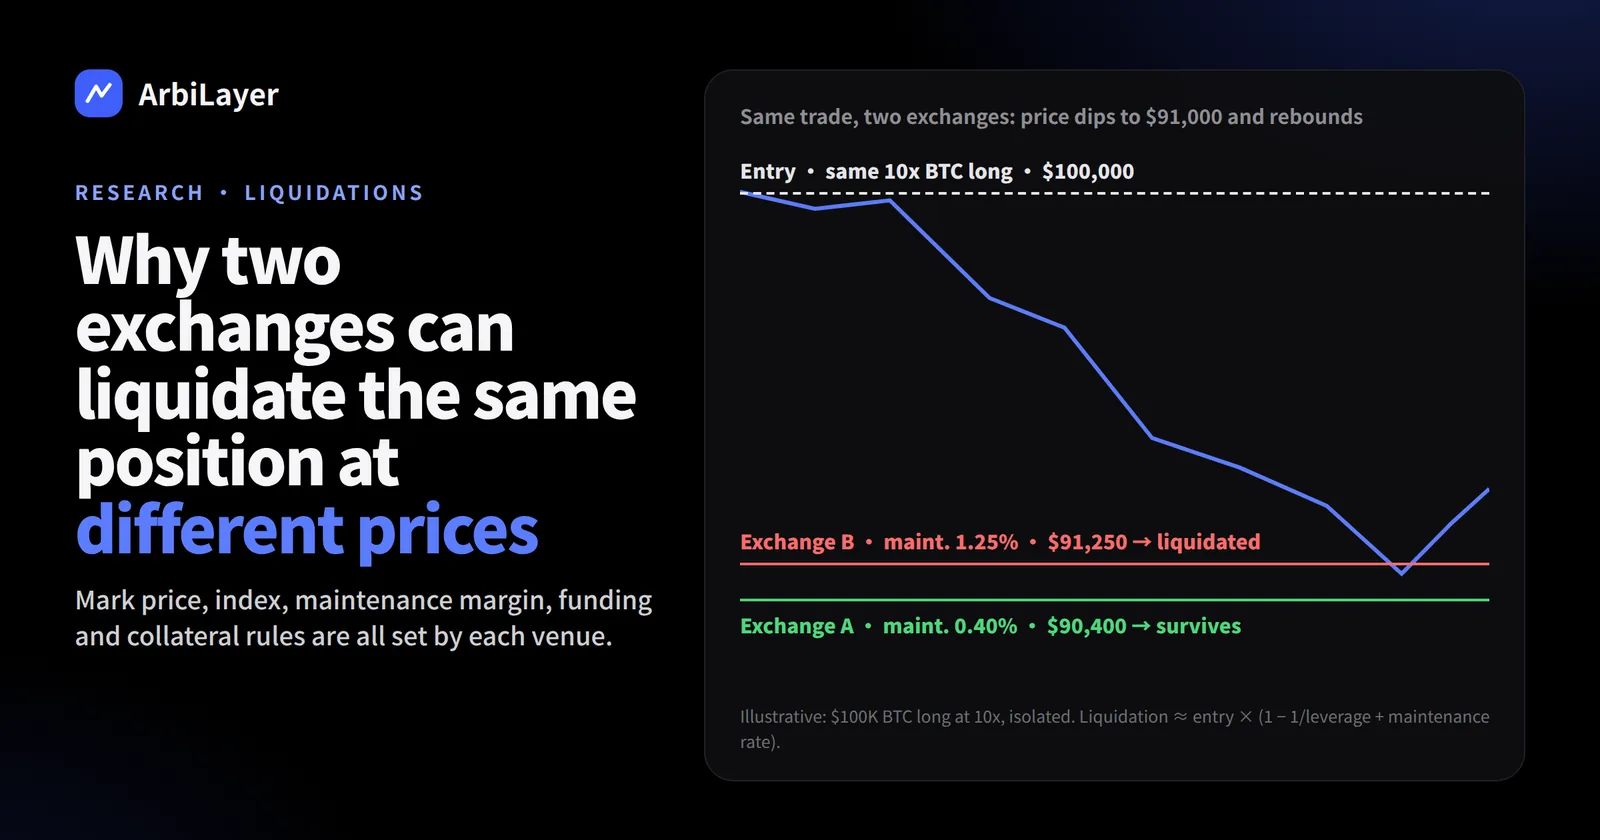 Why Two Exchanges Can Liquidate the Same Position at Different PricesMark price formulas, index constituents, maintenance margin tiers, funding and collateral rules are all set by each exchange — so the same l…
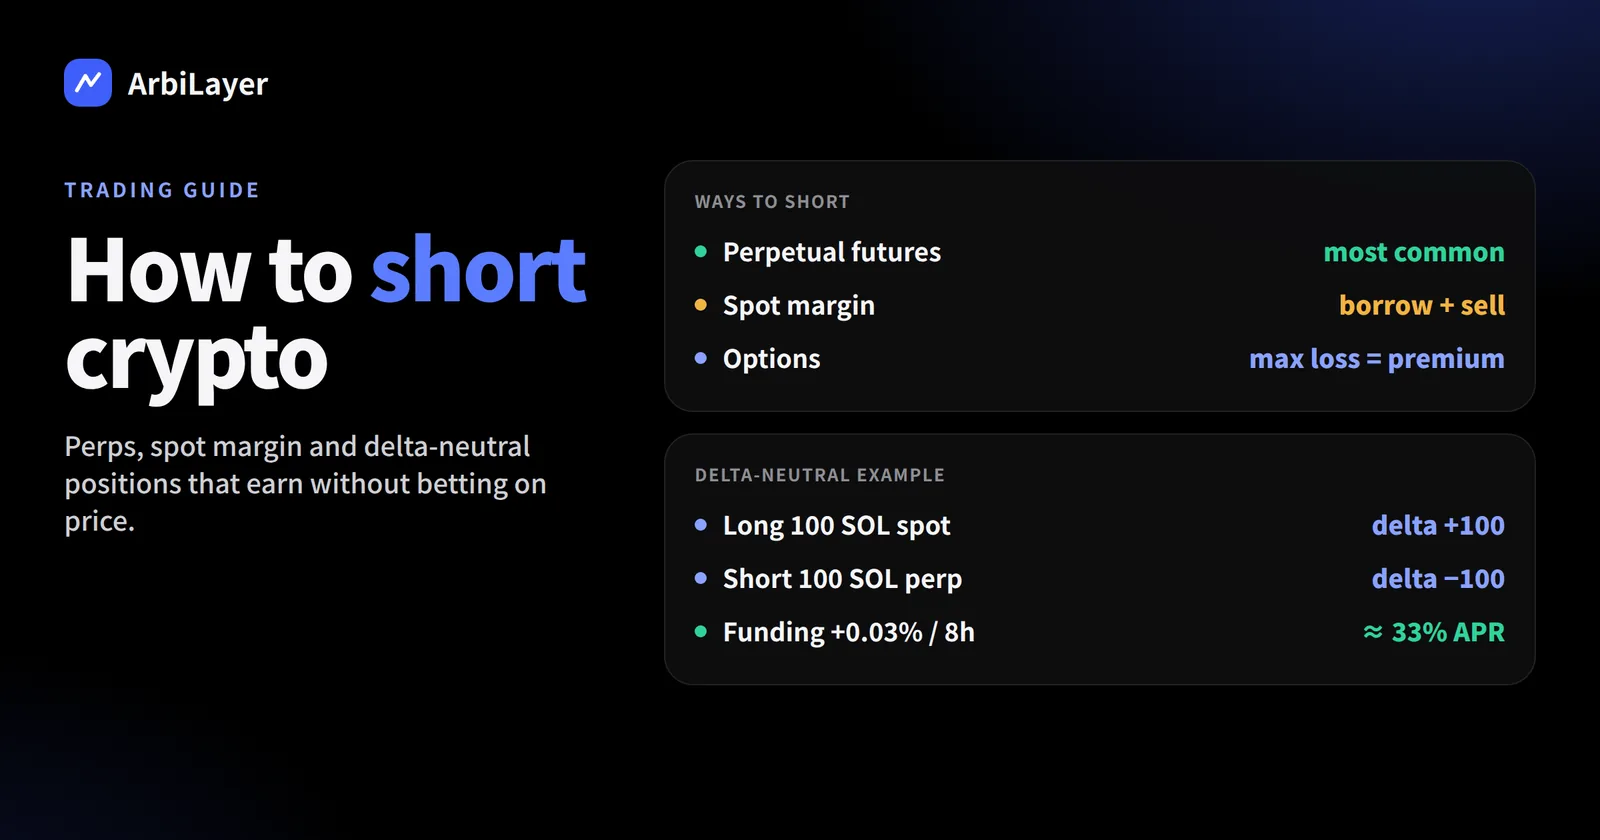 How to Short Crypto on Spot and Futures, and What Delta-Neutral MeansStep-by-step: shorting a coin with perpetual futures or spot margin, the costs (fees, funding, borrow interest), liquidation risk, and how d…